Seoul, October 28, 2026 – SK hynix Inc. (or “the company”, www.skhynix.com) announced today that it has recorded 104.6155 trillion won in revenues, 83.3338 trillion won in operating profit (with an operating margin of 80%), and 39.7756 trillion won in net profit (with a net margin of 38%) in the third quarter.
During the earnings presentation, CEO Kwak Noh-Jung explained the background of the company’s decisions regarding the Solidigm IPO and its principle to share the returns from strategic investment with shareholders.
“The IPO was intended to raise external capital for the expansion of Solidigm’s production facilities, and thereby to lighten our own investment burden and broaden our capacity for shareholder returns,” CEO Kwak said. “However, after carefully considering recent financial market conditions and other factors, we concluded that proceeding at this time would not be the best way to achieve the originally anticipated outcome. We have therefore discontinued our review.”
“Our principle has been to share the majority of the gains from successful strategic investments with our shareholders. These gains help replenish our capacity for shareholder returns, which may temporarily decline as we prepare for the future, allowing us to continue investing boldly in sustainable growth while protecting shareholder interests,” he continued. “In line with this principle, we have decided to return the gains realized from our investment in Kioxia this year to shareholders through a special dividend and we will remain committed to upholding this principle so that our shareholders can directly benefit from the returns from our strategic investments.”
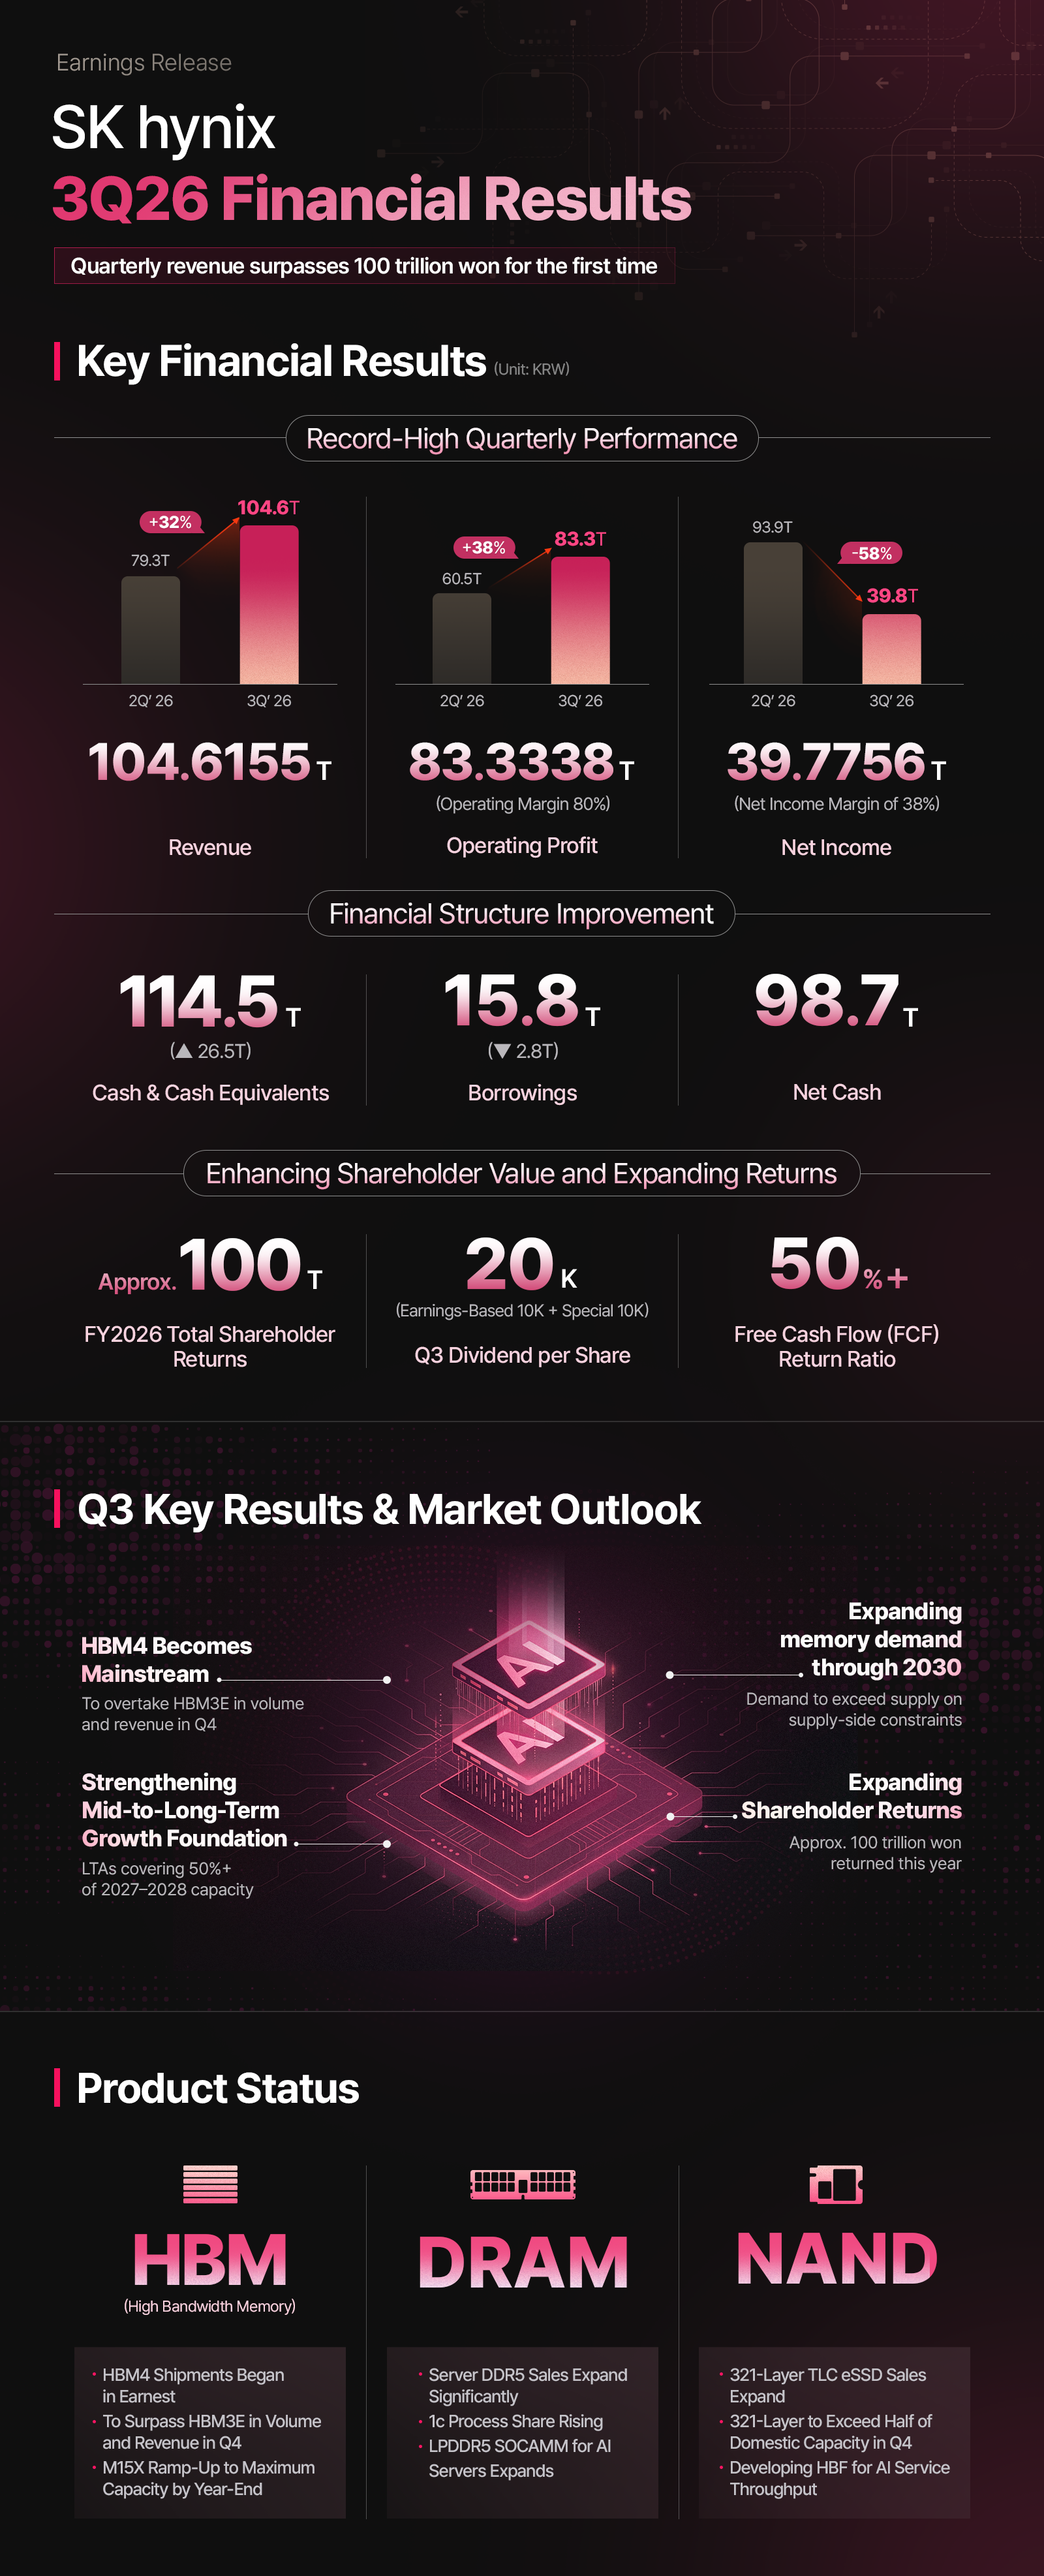
Record quarterly results in both revenue and operating profit and revenue surpasses 100 trillion won for the first time
In a market environment in which prices of key products have risen on the back of growing demand for AI memory, the company once again posted all-time-high quarterly results in both revenue and operating profit, underpinned by the competitiveness of its high-value-added products. In particular, revenue exceeded 100 trillion won for the first time in the company’s history. Revenue and operating profit increased by 32% and 38%, from the previous quarter, respectively.
* Q2 2026: Revenue of 79.3187 trillion won, Operating Profit of 60.5426 trillion won
By product, DRAM results were driven by a significant increase in sales of server DDR5 while HBM4 shipments began in earnest. In NAND, sales of 321-layer TLC eSSD expanded, and high-value-added products for data centers continued to grow across the board.
The company’s financial structure has also become significantly concrete. At the end of the third quarter, cash and cash equivalents stood at 114.5 trillion won, up 26.5 trillion won from the end of the previous quarter, while borrowings decreased by 2.8 trillion won to 15.8 trillion won. As a result, net cash increased to 98.7 trillion won.
Memory supply shortage to persist through 2030
SK hynix analyzed that a virtuous cycle has taken hold in which AI-driven productivity gains and new revenue generation in areas such as software development, customer service, and search lead to greater AI adoption, which in turn drives increased investment in infrastructure. It also projected that, as the drivers of AI investment move beyond the early stage, when a small number of companies accounted for most of it, and broaden to include general enterprises and nation-level initiatives, the global AI data center infrastructure market will continue to grow steadily.
The company likewise expects the memory market to sustain its growth, led in the short term by enterprise and personal AI and, over the mid-to-long term, by physical AI such as autonomous driving and robotics.
The company assessed that supply, on the other hand, is not keeping pace with the growth of the market. Given technical difficulty of leading-edge processes and the long lead time required to build new production facilities, it expects the structure in which demand exceeds supply to persist through 2030.
Expanding production capacity and strengthening product competitiveness to achieve a further step up in growth next year
Building on these favorable conditions, the company plans to accelerate the expansion of production capacity and the strengthening of product competitiveness in order to sustain the current growth momentum, and to scale up revenue and profit one step further next year.
First, the company plans to rapidly increase the portion of its 10nm-class 6th generation (1c) process technology and expand sales of DDR5 and LPDDR5 SOCAMM for AI servers, thereby further strengthening its DRAM portfolio centered on high-value-added products.
To respond to surging HBM demand, the company will ramp up M15X to maximum capacity by the end of the year to increase HBM4 production. Accordingly, the company expects HBM4 to surpass HBM3E in both shipment volume and revenue in the fourth quarter and to establish itself as a mainstream product.
In NAND, the company will raise the ratio of its 321-layer process to more than half of its domestic production capacity in the fourth quarter, and thereby increase the supply of high-performance, high-capacity eSSD. Over the mid-to-long term, the company intends to develop NAND into a core solution that enhances the throughput and economic efficiency of AI services, based on HBF and system optimization technologies.
Long-term agreements secured for more than 50% of 2027~2028 production capacity and the company to drastically expand investment next year
To improve mid-to-long term demand visibility and solidify its growth foundation, SK hynix is expanding long-term agreements (LTAs) with customers. The company has currently signed LTAs with 14 major customers, including leading global cloud service providers (CSPs), and is also proactively discussing with a number of customers the possibility of extending the contract terms, which are typically five years.
The LTA volume secured to date corresponds to more than 50% of total production capacity for 2027 and 2028. In particular, by introducing a mechanism that reflects market conditions within a price range agreed upon with customers, the company has established a structure that secures stable profitability while allowing flexible responses to market changes.
Backed by the demand visibility, the company is also moving to expand its production capabilities. Next year, with the Yongin Phase 1 entering full-scale operation and domestic and overseas infrastructure investment gaining momentum, investment is expected to increase significantly. The company nevertheless plans to adjust the scale and timing of its investment flexibly, after carefully weighing customer demand, product competitiveness, profitability and investment efficiency.
Most of the gains from the Kioxia investment to be shared with shareholders, with approximately 100 trillion won in shareholder returns to be executed this year
As previously indicated in August, SK hynix announced its additional shareholder return plan. For fiscal year 2026, the company will pursue shareholder returns totaling approximately 100 trillion won, comprising cash dividends of 30 trillion won or more and share repurchases and cancellations of 60 trillion won or more in total, including the 40 trillion won announced in August. Through this, the company intends to fulfill its commitment to return 50% or more of free cash flow (FCF). Of this, the 40 trillion won share repurchase announced in August was completed last week, and the shares will be cancelled shortly.
The company also set out its principles: the dividend amount will be determined on the basis of operating results; if significant investment gains arise, they will be returned additionally through special dividends; and share repurchases will continue every quarter.
At today’s meeting, the Board of Directors resolved on a third-quarter cash dividend of 14 trillion won and a share repurchase of 20 trillion won. Of the shares to be repurchased, 10 trillion won, earmarked for shareholder returns, will be cancelled in full, while the remaining approximately 10 trillion won will be used for employee compensation and is not included in the shareholder return total.
The third-quarter dividend is 20,000 won per share, consisting of a 10,000-won dividend reflecting improved earnings and a 10,000 won special dividend that shares the gains from the Kioxia investment. The company has decided to return to shareholders most of the gains realized from its Kioxia investment this year.
“The customer trust built through our technological competitiveness is leading to long-term contracts, and our business structure is transforming into one with earnings stability and mid-to-long term demand visibility,” CEO Kwak emphasized. “We will carry our HBM competitiveness over to next-generation products, and we will also increase the rewards we share with our shareholders as our business outcome and investment result grow.”
■ 3Q26 Financial Results (K-IFRS)
|
Unit: Billion KRW
|
※ Financial information of the earnings is based on K-IFRS
※ Please note that the financial results discussed herein are preliminary and speak only as of October 28, 2026. Readers should not assume that this information remains operative at a later time.
※ Percentage changes are calculated on the basis of unrounded figures.
Disclaimer
This material has been prepared by the Company for informational purposes only, and the information contained herein has not undergone any separate, independent verification process. No representations or warranties are made regarding the fairness, accuracy, or completeness of the information contained in this material, and such information should not be relied upon. Neither the Company nor its employees bear any civil, criminal, or administrative liability for any damages arising from this material or from its use.
Review of the FY2026 Q3 financial results has not been finalized. Figures in this earnings release are subject to changes during the independent auditing process.
All financial information contained in this document is based on consolidated K-IFRS.
This material contains forward-looking statements, which involve risks and uncertainties. These statements are generally identified words such as “may,” “will,” “intend,” “should,” “believe,” “expect,” “anticipate,” “project,” “estimate” and similar expressions, or the negative of such expressions. Forward-looking statements are not guarantees of future performance and are subject to inherent risks, uncertainties, and other factors that could cause actual results to differ materially from those expressed or implied. Readers are cautioned not to place undue reliance on any of these forward-looking statements. These forward-looking statements speak only as of the date hereof. SK hynix undertakes no obligation to update any of these forward-looking statements to reflect events or circumstances after the date of this news release or to reflect actual outcomes, unless required by law.
This material does not constitute a solicitation for the acquisition or purchase of securities, and no part of this material should serve as the basis for any contract, agreement, or investment decision, nor should it be relied upon in connection therewith.
About SK hynix Inc.
SK hynix Inc., headquartered in Korea, is the world’s top tier semiconductor supplier offering Dynamic Random Access Memory chips (“DRAM”) and flash memory chips (“NAND flash”) for a wide range of distinguished customers globally. The Company’s shares are traded on the Korea Exchange, and the Global Depository shares are listed on the Luxembourg Stock Exchange. Further information about SK hynix is available at www.skhynix.com, news.skhynix.com.
Media Contact
SK hynix Inc.
Global Public Relations
Technical Leader
Minseok Jang
E-Mail: global_pr@skhynix.com